
Published September 6, 2026
Do You Really Need 20% Down to Buy a Home?
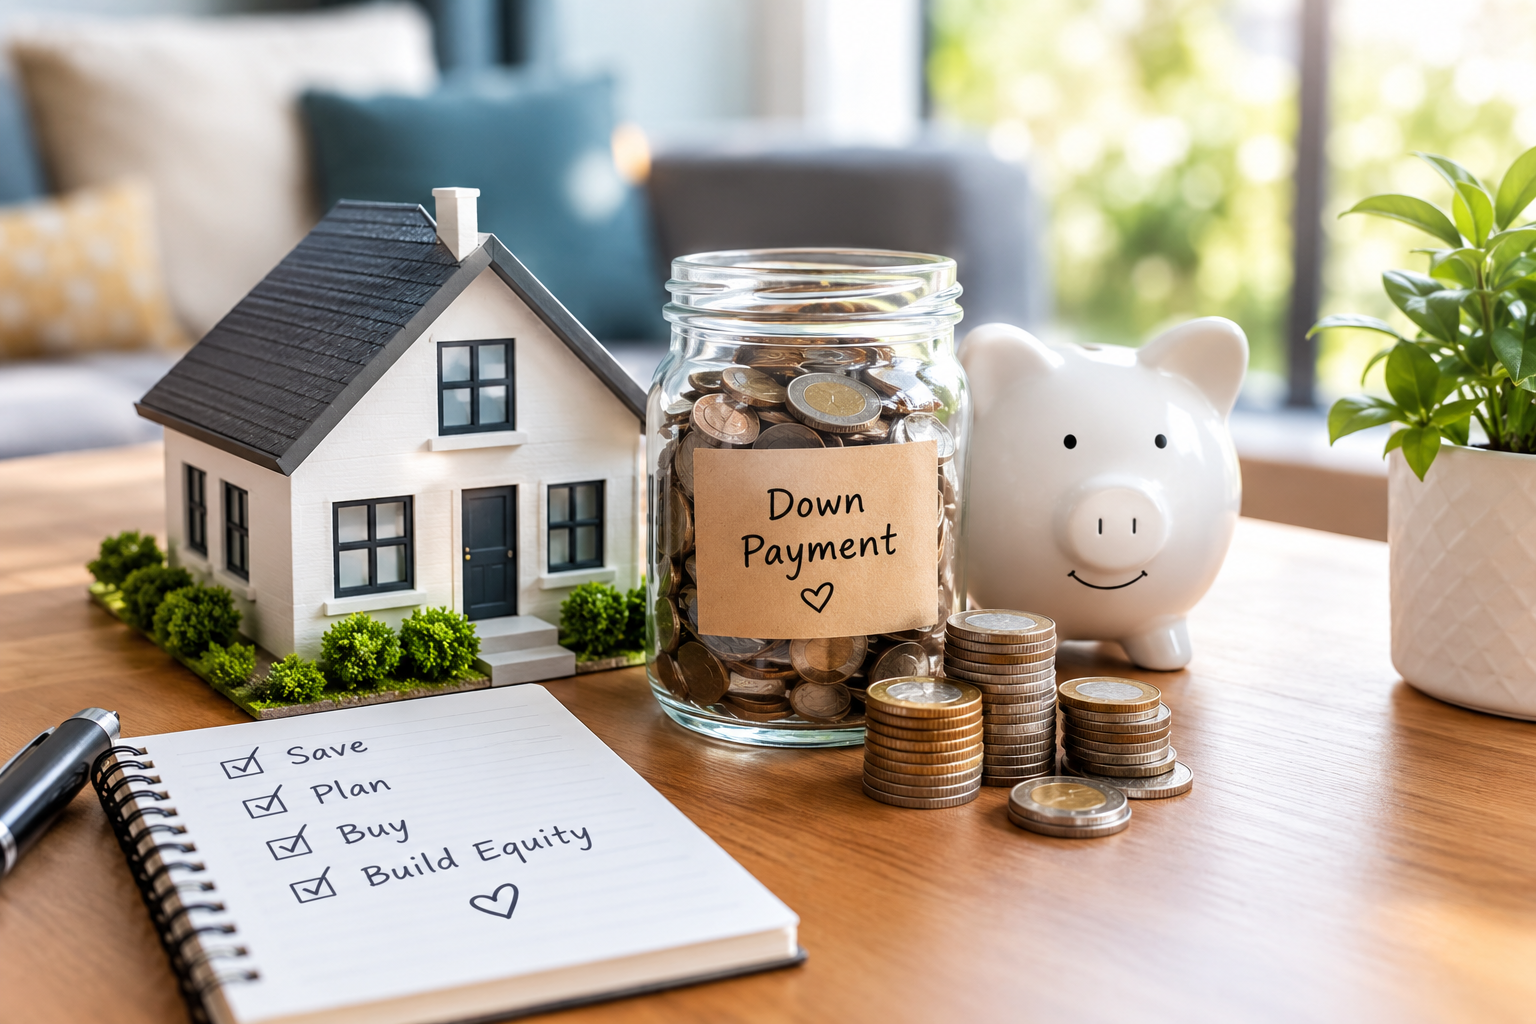
If you’ve been thinking about buying a home, you may have heard the familiar advice: “You need 20% down.”
The good news? That isn’t necessarily true.
While putting 20% down can have some advantages, many homebuyers purchase homes with significantly less. Understanding your options can help you make a smarter decision based on your finances, goals, and the type of home you want to buy.
Why Does Everyone Talk About 20%?
A 20% down payment can help you avoid private mortgage insurance (PMI) on many conventional loans. It also means you start your homeownership journey with more equity in the property.
For example, on a $300,000 home:
- 20% down = $60,000
- 10% down = $30,000
- 5% down = $15,000
- 3% down = $9,000
For many buyers, saving $60,000 can take years. Waiting until you have that much money could mean delaying homeownership longer than necessary.
There Are Loan Options With Lower Down Payments
Depending on your qualifications, there may be mortgage programs that allow you to purchase with a much smaller down payment.
Some conventional programs may allow down payments as low as 3%, while other loan programs may have different requirements.
The important thing is that there isn't one down-payment amount that works for everyone.
Your lender can help you understand which programs you may qualify for and what your estimated monthly payment and upfront costs could look like.
Don't Forget About Closing Costs
One mistake first-time buyers sometimes make is focusing only on the down payment.
Buying a home can involve additional expenses such as:
- Loan-related costs
- Appraisal fees
- Inspections
- Title and recording expenses
- Prepaid taxes and insurance
- Homeowners insurance
- Other transaction-related expenses
That's why it's important to look at your total cash needed to purchase, rather than simply asking, “How much is the down payment?”
Should You Put More Money Down?
A larger down payment isn't automatically better.
Putting more money into the home can reduce the amount you borrow, potentially lowering your monthly principal and interest payment. However, you also don't want to drain your savings just to reach a certain down-payment percentage.
Homeownership comes with ongoing expenses, and having money available for emergencies, maintenance, moving costs, and other unexpected expenses can be valuable.
The right question isn't necessarily:
“How can I put 20% down?”
Instead, consider asking:
“What down payment makes sense for my financial situation?”
Start With a Conversation
If you're considering buying a home in the Triad, you don't have to have everything figured out before you start exploring your options.
A conversation with a qualified lender can help you understand your potential purchasing power, while a knowledgeable real estate professional can help you understand the local market and what your budget may realistically buy.
You may discover that homeownership is closer than you thought.
Ready to Explore Your Options?
Whether you're a first-time buyer, moving to a new home, or simply curious about what's possible, the Terri Bias Team is here to help you take the next step.
Don't let the idea that you need 20% down keep you from exploring your options. Start with a conversation, learn what may be available to you, and build your home-buying plan from there.
Your next home may be closer than you think.